A Public Adjuster for St. Charles, Missouri Homeowners and Business Owners
St. Charles sits right on the Missouri River, in one of the fastest-growing counties in the state — a mix of 250-year-old riverfront neighborhoods and brand-new subdivisions still being built out toward Wentzville. That growth is a good thing, but it also means a lot of property here has never been through a serious insurance claim before, and it’s easy to assume your insurance company’s first number is the final one.
Deskar 6 is a licensed public adjusting firm. We represent you, not your insurance carrier. We inspect the damage, document the full scope of loss, and negotiate directly with your insurer so your settlement reflects what repairs actually cost.
No upfront fees. We only get paid when you do.
St. Charles Has Already Seen What a Bad Storm Season Looks Like
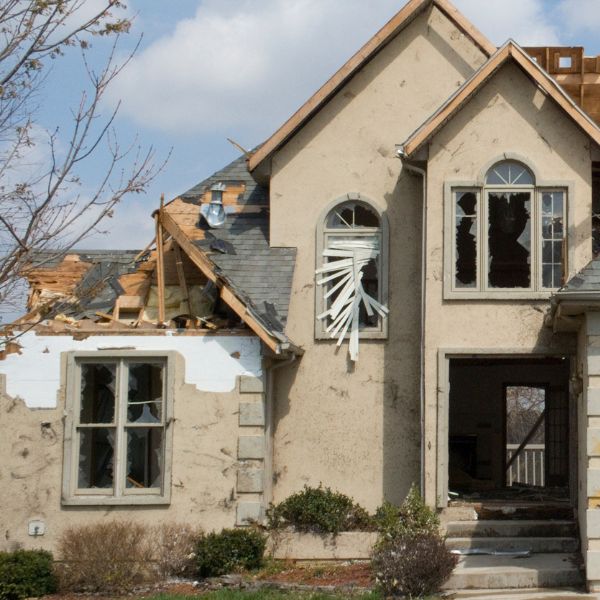
In late July 2022, the St. Louis region recorded its heaviest rainfall in history, and St. Charles County was one of the counties named in the federal disaster declaration that followed. In February 2024, a single hailstorm across the bi-state area generated thousands of claims from one insurer alone. Between the two, most long-time St. Charles homeowners have either filed a claim themselves or watched a neighbor go through one.
What that history really shows is how often a first insurance estimate misses something — a damaged slope the adjuster didn’t walk, hail impact on soft metal that’s easy to overlook, or water damage that traces back to more than one source. A second, independent look at the claim costs nothing and often finds real gaps.
Flood or Wind? Why the Difference Matters on the Missouri River
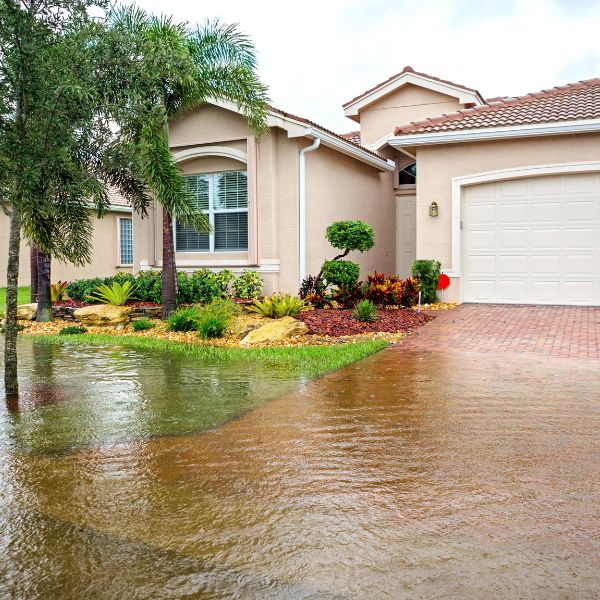
Living on the river means a claim here can involve a distinction a lot of other cities don’t have to think about as often: the difference between wind-driven rain damage (typically covered under a standard homeowners policy) and rising-water flood damage (which usually isn’t, and requires separate National Flood Insurance Program coverage).
After a bad storm, it’s common for a single loss to involve both — wind tore something open, and water got in on top of that. Sorting out which policy covers which part of the damage is exactly the kind of detail that can shrink a settlement if nobody pushes back on it. We help make sure the right coverage is applied to the right damage, instead of the whole loss getting quietly filed under whichever category pays less.
What We Handle for St. Charles Properties
- Storm, wind, and hail damage — roofs, siding, gutters, and soft-metal components (AC fins, downspouts) that are often the clearest sign hail actually hit a property, even when shingles look fine at a glance
- Missouri River and heavy-rain flooding — including claims connected to major regional flood events and everyday drainage and basement intrusion issues
- Fire and smoke damage — structural, contents, and smoke-odor documentation
- Winter freeze and frozen pipe damage
- Commercial and multifamily claims — relevant to the retail and apartment development around The Streets of St. Charles and the county’s fast-growing commercial corridors
Built Around How People Actually Live and Work Here
A lot of St. Charles households work shifts tied to the county’s major employers — GM’s Wentzville Assembly Plant, Boeing, and others — which doesn’t leave much room for open-ended daytime availability during a claim. We work around that, not the other way around.
And if your property is in one of St. Charles’s historic districts — South Main, Frenchtown, or the Historic Downtown area — repairs to original siding, windows, or roofing may need Landmarks Board approval, which can add cost and time that a generic insurance estimate won’t account for. We factor that into the claim from the start.
Our Process
Free Claim Review
A no-cost look at your situation, whether you've filed already or not.
Property Inspection
We walk the property and document visible and hidden damage.
Policy and Estimate Review
We compare your policy and the insurer's estimate against the real scope of repair.
Claim Documentation
A complete, photo- and measurement-backed claim package.
Insurance Company Negotiation
We handle the back-and-forth with the carrier.
Settlement Support
We help you understand the outcome before repairs begin.
Homeowners We’ve Helped:
Real homeowners. Real claims. Real results.
Posted on Google
 Lisa Albright
Trustindex verifies that the original source of the review is Google.
They were great to work with. Very professional and made the experience stress free. Would highly recommend them.Posted on Google Benjamin KhachaturianI worked with Deskar6 on a roof claim and I can only say great things! I’m very grateful that Marty & Melissa could help with my roof claim. Very kind over the phone in helping me understand the process since it was my first claim. Highly recommend Deskar6! ☺️✅Posted on Google
 Carmon SmithI am so glad I found Deskar 6!!! I didn’t realize how important a loss adjuster helps when you need work done on your home. Going forward I will be working with a loss adjuster.Posted on Google
 Julia BouchardMy public claims adjuster made my insurance claim easy to understand and i’m happy with the settlement.Posted on Google
 Bailey TooheyWhen our roof got damaged in a storm, we tried dealing with the insurance ourselves big mistake. Deskar 6 LLC was recommended by a friend, and they made all the difference. Their loss adjuster handled everything fast and professionally. They’re legit and truly care about their clients.Posted on Google
 Bailey McGrathI didn’t even know what a loss adjuster did until I worked with Deskar 6 LLC now I’ll never file an insurance claim without them. They handled the back-and-forth with my insurance company like pros and got me a much better settlement than I expected. Extremely professional and worth every penny.Posted on Google
 Elizabeth WymarkI had a great experience working with Deskar 6 LLC. They were professional, responsive, and handled everything smoothly from start to finish. It's hard to find companies that actually deliver on their promises these guys did.Posted on Google
 Carlos LopezMartin was great, he’s really trying to help homeowners get the coverage they deserve.
We Also Serve Nearby Communities
St. Charles is our focus here, and we also work with homeowners and business owners throughout St. Charles County, including St. Peters and Wentzville. If you’re unsure whether we cover your specific address, just call — we’ll tell you plainly.
Frequently Asked Questions — Public Adjusters in St. Charles, MO
Does Missouri cap what a public adjuster can charge?
No. Missouri does not set a fee cap on public adjuster contingency fees, which makes it especially worthwhile to understand a fee structure clearly before signing anything, and to compare it against the value of the additional settlement recovered.
How do I know a public adjuster is legitimate, especially right after a storm?
Missouri’s Department of Insurance has specifically warned homeowners about adjusters and solicitors who show up quickly after a disaster. Ask for a Missouri license number, confirm it’s active, and be cautious of anyone pushing you to sign before you’ve had time to think it over.
Is it true that a claim check has to include my name, not just the adjuster's?
Yes. Missouri regulation requires that any insurance payment involving a public adjuster name the policyholder as a joint payee on the check — it should never be issued to the adjuster alone.
Does my homeowners policy cover flooding from the Missouri River?
Typically not. Rising-water flood damage generally requires separate National Flood Insurance Program coverage, while wind-driven rain damage is usually covered under a standard homeowners policy. Since storms here often cause both at once, sorting out which applies to which part of the damage really matters.
My insurance company already inspected after the 2022 flood or a hailstorm — is it too late to do anything?
Denied, or new damage has since turned up, many claims can still be supplemented or reopened depending on your policy and timing. A free review can tell you where things stand.
Do you help with claims on historic homes in Frenchtown or South Main?
Yes. Historic-district repairs often involve Landmarks Board approval and period-appropriate materials, which can add real, legitimate cost to a repair that a first estimate may not reflect.
Get a Free Insurance Claim Review in St. Charles, MO
No obligation. No pressure. Just a clear, independent look at where your claim stands.